
BUSINESS LINE OF CREDIT
FOR YOUR SMALL BUSINESS
Funds in 2 - 5 days
Finance $10,000 to $5 million
Terms from 12 months to 5 years
Get Started Today And Speak With an Advisor
WHAT IS A BUSINESS LINE OF CREDIT?
A business line of credit is a flexible financing option that allows businesses to borrow funds as needed, similar to a credit card. Interest is paid only on the borrowed amount, and funds can be used for various purposes like managing cash flow or covering unexpected expenses. Once repaid, the credit becomes available again, making it a revolving form of credit that can be accessed repeatedly.

SIMPLE APPLICATION
Our simple 15-second online application can get you matched with offers in minutes.
LARGER AMOUNTS
Get matched with the best financing options with the highest funding amounts.
NO MINIMUM FICO
Bad credit? No problem! Most of our top financing options have no minimum FICO.
SAME DAY FUNDING
Our fintech speed can get you in and out of Underwriting in just a few hours – and same day funding!
WHAT DO YOU NEED TO QUALIFY

3+ MONTHS In Business
You can qualify for our top financing options with as little as 3+months in business.

$ 5,000 + Monthly Gross Sales
The minimum revenue to qualify for financing options are $5,000 per month, or $60,000 in annual gross sales.

No Minimium FICO
We have financing options for all credit profiles. There is no minimum FICO score required to apply.
WHY ESHE FINANCIAL?
Stellar Reputation
Backed by thousands of 5-star reviews, our business financing experts will work with you to solve your business challenges.
Technology- Fisrt Control
ROK Intelligence uses AI to streamline the funding process. Get an instant pre-approval and flexible loan options that fit your business needs.
Multi Options
Choose an offer that makes the most sense for you and your business. Compare offer terms and choose what works best.
Zero Suprises
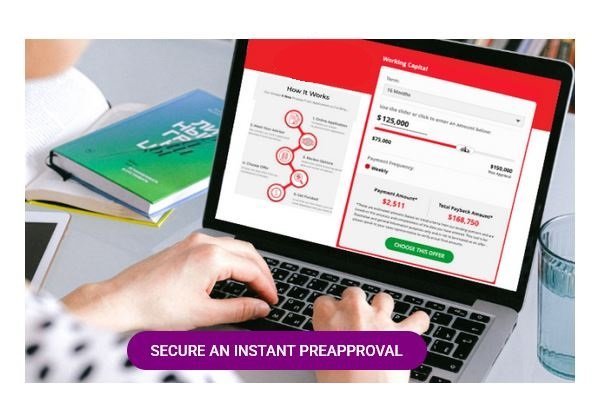
ROK's offer calculator takes the guesswork out of business financing. It provides full transparency on terms. One fee, no surprises.
STEP 1: APPLY ONLINE
Secure an instant pre-approval. Our application process is straightforward and can be completed in seconds.
STEP 2: REVIEW OPTIONS
Your personal loan advisor will discuss finance options available with you for your business.
STEP 3: RECIEVE YOUR FUNDS
Finish the online application process and receive your funds in as little as 24 hours.
Business Line of Credit for Your Business
A business line of credit can be helpful when your expenses don’t always line up with your revenue. You may need to purchase inventory today, cover an operating expense next month, or handle an unexpected business cost along the way.
Eshe Financial helps businesses across the United States explore business line of credit options based on their financing needs, financial circumstances, and available financing programs.
How a Business Line of Credit Works
A business line of credit gives an eligible business access to a set amount of credit that can be used when needed, rather than requiring the full amount to be taken upfront.
For example, you might use part of your available credit to purchase inventory and later draw additional funds for another business expense. With a revolving line of credit, the amount you repay may become available to use again, depending on the terms of your financing agreement.
Interest, fees, repayment schedules, and other costs can vary between financing programs. Before moving forward, take the time to understand how the line works, what costs may apply, and what repayment terms are included in the agreement.
Business Line of Credit vs. Business Loan
A business line of credit and a business loan can both give you access to business capital, but they work in different ways and may be better suited to different financing needs.
Business Line of Credit | Business Loan |
Draw funds as needed | Receive a specific amount upfront |
Useful when expenses can change | Often used for a planned expense |
May offer revolving access | Usually follows a set repayment schedule |
Borrow only the amount you need | Receive the financed amount at the start |
Available credit may become available again as you repay, depending on the agreement | Typically involves one financing transaction |
The right financing structure depends on your business needs, cash flow, eligibility, and the terms available to your business.
What Can You Use a Business Line of Credit For?
Business expenses don’t always arrive on schedule. A line of credit may give eligible businesses another way to handle certain costs as they come up, depending on the financing program.
Inventory and Supplies
If your business regularly purchases inventory, materials, or supplies, a line of credit may help cover those costs while keeping more of your cash available for other business needs.
Day-to-Day Operating Costs
Expenses such as rent, payroll, utilities, and business supplies can sometimes put pressure on cash flow. A line of credit may provide access to capital when expenses come due before expected revenue arrives.
Business Expansion
Growth can bring new expenses. You may need more inventory, additional employees, increased marketing, or other resources as your business expands.
Unexpected Business Expenses
Unexpected costs can come up in any business, from equipment repairs to urgent purchases. Having access to available credit may provide another option for handling these expenses when they arise.
Short-Term Working Capital Needs
If there’s a temporary gap between money going out and money coming in, a business line of credit may be one option for managing short-term working capital needs.
Available uses, financing terms, and restrictions vary by lender and financing program.
When Should You Consider a Business Line of Credit?
A business line of credit may be worth exploring when your expenses change from month to month or your cash flow doesn’t always line up with when payments are due.
It may be worth considering if your business:
- Has seasonal changes in revenue
- Needs additional working capital from time to time
- Purchases inventory throughout the year
- Has a gap between completing work and receiving customer payments
- Deals with recurring short-term expenses
- Wants access to capital without taking the full amount upfront
Before choosing a financing option, consider the total cost, repayment terms, fees, and how the payments would fit into your business’s regular cash flow.
Understanding Business Line of Credit Costs and Terms
The available credit amount is only one part of the overall picture. The cost and terms of a business line of credit can vary depending on the financing program and your business’s financial circumstances.
Before accepting an offer, take a close look at:
- Interest rate or applicable financing cost
- Origination and other fees
- Available credit limit
- Draw and repayment terms
- Payment frequency
- Renewal requirements
- Any restrictions on how the funds can be used
- Total cost of financing
Taking a few minutes to review these details can make it easier to compare your options and understand whether the financing fits your business’s needs.
Documents You May Need for a Business Line of Credit
The documents you need can vary depending on the lender and financing program. You may be asked to provide information that helps verify your business, revenue, and overall financial position.
This may include:
- Business identification and contact information
- Ownership information
- Revenue details
- Recent bank statements
- Business tax returns
- Financial statements
- Information about existing business debt
- Personal or business credit information
- Details about how you plan to use the funds
Keeping your financial records up to date can make it easier to explain your financing needs and explore the options available to your business.
Managing a Business Line of Credit Responsibly
Having access to additional capital doesn’t mean you need to use all of it. Keeping track of what you borrow and how repayment fits into your regular cash flow can help you stay on top of your financing.
It’s helpful to keep an eye on:
- Available credit
- The amount you’ve drawn
- Upcoming payments
- Interest and other financing costs
- Current business cash flow
- Your repayment plan
Reviewing these details regularly can help you understand how much credit you’re using and keep your financing aligned with your business’s financial needs.
Business Line of Credit for Businesses Across the U.S.
Every business has different financing needs based on its industry, size, cash flow, and stage of growth. A seasonal business may need extra working capital during busy periods, while a growing company may need funds for inventory, staffing, or expansion.
Eshe Financial works with businesses across the U.S. to help them explore available financing options. Requirements, rates, terms, funding amounts, and approval decisions can vary depending on the business and the financing program.
Explore Your Business Financing Options
A business line of credit is one of several ways to access business capital. Depending on your needs, you may also want to explore small business loans, SBA loans, equipment financing, working capital financing, or other business financing options.
If you’re considering a line of credit, start by asking three simple questions: How much capital do you need? What will you use it for? And how would repayment fit into your business’s cash flow?
Once you have a clearer picture of your needs, you can explore the available financing options and review the terms that apply to your business.
Frequently Asked Questions
What is a business line of credit?
A business line of credit gives an eligible business access to a set amount of credit that can generally be drawn as needed, subject to the terms of the financing agreement.
How is a business line of credit different from a business loan?
A business loan typically provides a specific amount upfront, while a business line of credit may allow you to draw funds as needed. Repayment terms, fees, and financing costs can also vary.
What can I use a business line of credit for?
Depending on the financing program, funds may be used for expenses such as inventory, working capital, operating costs, business expansion, and unexpected business expenses.
How much can I get with a business line of credit?
The available credit amount varies by financing program and the business’s circumstances. Factors such as revenue, cash flow, credit information, existing obligations, and other financial details may be considered.
What documents do I need for a business line of credit?
Requirements vary by lender and financing program. You may be asked for business and ownership information, revenue records, bank statements, tax returns, financial statements, and other financial information.
Can I get a business line of credit with less-than-perfect credit?
Credit requirements vary by financing program. Providers may consider credit information along with revenue, cash flow, time in business, existing obligations, and other factors when reviewing an application.
